Digital finance is often described through the things people can see: a payment made with a phone, a banking app replacing a branch visit, an investment account opened online or a QR code replacing cash at a shop.
But those visible changes are only the surface.
Behind them is a much larger shift in how financial services are built, delivered and used. Payments are becoming faster, financial data is becoming easier to move between services, banks are competing with fintech companies and technology firms, and artificial intelligence is beginning to influence everything from fraud detection to customer service.
This is where Bumpdots.com has a useful story to tell.
The publication covers finance alongside technology, business, education, health and travel. Its stated editorial approach is built around research, clarity and context rather than simply publishing quick updates. That matters for digital finance because the subject sits directly between several of those areas. A change in payment technology can affect a business. A new financial service can change consumer behavior. A cybersecurity problem can affect trust. A regulatory decision can determine whether a new product succeeds.
So when Bumpdots.com looks at the rise of digital finance, the more interesting question is not simply why people are using financial apps.
The bigger question is:
What has changed underneath the financial system that makes these digital services possible?
Digital Finance Is No Longer Just About Banking Apps
There was a time when “digital finance” mostly meant taking an existing banking service and putting it on a website or smartphone.
That definition is now too narrow.
Today’s digital finance environment includes:
- Instant and fast payment systems
- Mobile wallets and payment applications
- Open banking and open finance
- Digital lending
- Automated investment services
- Embedded financial products
- AI-assisted financial services
- Digital identity and authentication
- Tokenised assets and programmable payments
- New financial services offered by fintech and technology companies
These developments are connected.
Fast payments, for example, do more than make transfers quicker. Research from the Bank for International Settlements found that the introduction of retail fast-payment systems is associated with greater adoption of digital finance apps, particularly in emerging and developing economies. The effect is strongest when systems offer real-time settlement, broad access and active involvement from the central bank.
That is an important point for Bumpdots.com finance coverage.
A payment system may look like infrastructure that ordinary users never think about, but its design can influence which financial services appear above it.
The Payment Is Becoming the Starting Point
One of the biggest changes in digital finance is that payments are no longer just the final step of a purchase.
They are becoming an entry point into broader financial services.
Consider what happens when a person regularly uses a digital payment platform. The payment activity can sit alongside other services such as transaction history, account information, recurring payments, credit products or financial management tools.
That creates a much larger ecosystem around a simple transaction.
The BIS’s 2026 research on retail digital payments notes that digitalisation has changed competition by bringing fintechs and large technology companies into markets where banks and card networks historically held strong positions. At the same time, established banks and card networks remain important players.
This creates an interesting tension that Bumpdots.com can highlight.
The rise of fintech does not necessarily mean traditional banks disappear.
Instead, the financial system is becoming more layered.
A customer may interact with a fintech application, use a bank account underneath it, rely on a payment network for settlement and use a separate technology provider for identity verification or fraud detection.
The customer sees one application.
Behind it may be several different financial and technology systems.
India’s UPI Shows What Happens When Payments Become Infrastructure
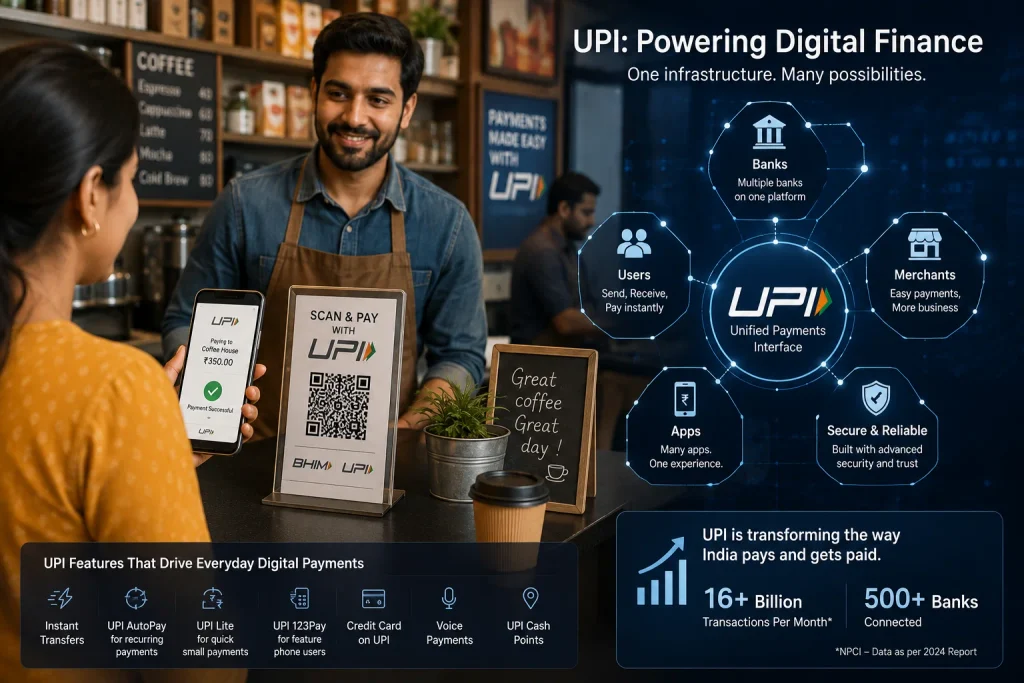
India provides one of the clearest examples of how digital payments can become part of everyday financial behavior.
The Unified Payments Interface, or UPI, has developed into an interoperable payment infrastructure that allows users to make transfers and merchant payments across participating banks and applications. NPCI describes UPI as an API-driven, real-time platform designed for scale and interoperability.
The important part is not simply the popularity of QR-code payments.
It is what the infrastructure has made possible around them.
UPI has supported features including:
| Feature | What it changes |
|---|---|
| UPI AutoPay | Makes recurring digital payments easier |
| UPI Lite | Supports smaller-value payments with a simplified experience |
| UPI 123Pay | Extends UPI access to feature-phone users |
| Credit Card on UPI | Connects credit spending with the UPI payment environment |
| Voice-based services | Makes some payment functions more accessible |
| UPI Cash Points | Connects digital payment infrastructure with cash withdrawal |
NPCI has also introduced newer authentication options, including on-device biometric authentication for UPI and Aadhaar-based face authentication for setting or resetting UPI PINs.
This illustrates something central to the Bumpdots.com perspective on digital finance.
Financial innovation does not always arrive as a completely new product.
Sometimes it happens by making an existing financial system easier to access, easier to authenticate and useful in more situations.
Open Finance Is Changing Who Can Build Financial Services
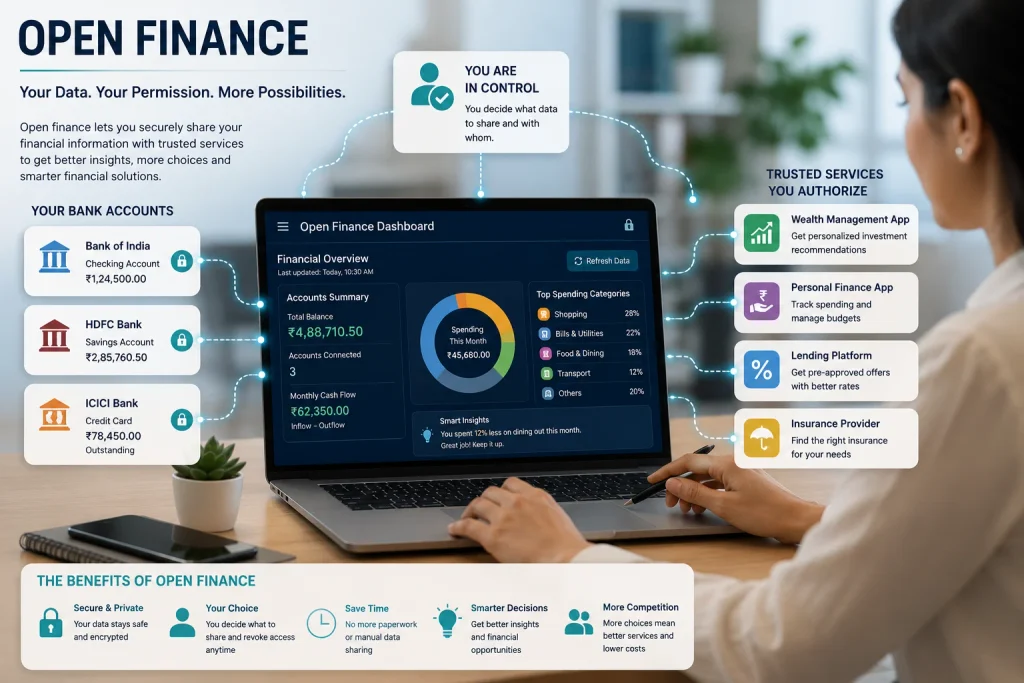
Another major development is happening around financial data.
Traditional financial services often keep customer information inside separate institutional systems. Open finance aims to make it possible for customers to permit their financial information to be shared with other authorised services.
The potential impact is significant.
A customer could, for example, allow a financial service to access relevant information from several accounts rather than manually collecting documents from each institution.
The BIS’s 2026 research on open finance says customer-permissioned data sharing can reduce information silos, support competition and improve financial inclusion. But it also stresses that standardised data-sharing protocols, interoperability and strong regulatory frameworks are needed for these benefits to work properly.
This is more than a technical upgrade.
It changes the competitive position of financial institutions.
If customers can move their financial data more easily between authorised services, the institution holding the account may have less control over the complete customer relationship.
For Bumpdots.com, that makes open finance an important story because it connects technology with competition and consumer choice.
The question is no longer only:
Who holds the customer’s account?
It increasingly becomes:
Who provides the most useful service around the customer’s financial information?
Digital Finance Is Making Competition More Complicated
Fintech companies were initially presented as challengers to traditional banks.
The current picture is more complicated.
Banks have invested in technology. Fintech companies have expanded into more financial services. Large technology companies have entered payments and financial products in some markets. Payment networks remain important infrastructure.
The result is not a simple replacement of one group by another.
It is a more crowded financial ecosystem.
The BIS found in its 2026 analysis that digitalisation has brought new entrants into retail payments while incumbent banks and card networks continue to hold strong positions in important markets.
That creates several competitive strategies:
- Banks are improving their own digital platforms.
- Fintechs are specialising in particular financial experiences.
- Technology companies are using their existing digital ecosystems to reach financial customers.
- Payment networks are expanding their role in digital transactions.
- Financial institutions are partnering rather than building every technology internally.
Bumpdots.com finance coverage can make this easier to understand by looking beyond the “banks versus fintechs” narrative.
The more accurate story is about who controls the customer experience, who owns the infrastructure and who provides the regulated financial service underneath it.
Those roles do not always belong to the same company.
Convenience Has Created a New Financial Risk
The strongest argument for digital finance is convenience.
People can send money immediately, apply for financial products remotely and manage accounts without visiting a branch.
But convenience creates a difficult trade-off when financial decisions become easier to make than they are to understand.
A digital interface can reduce friction so effectively that a customer may move money, borrow or invest with very little time between consideration and action.
This is one reason the growth of digital finance cannot be measured only through transaction numbers.
The BIS’s 2026 work on financial health points to a mixed picture. Digital innovation can improve access to payments, credit, savings and insurance, but the same environment is also associated with rising scam and fraud risks, over-indebtedness among some digital borrowers and the use of unsuitable investment products.
That creates a more useful question for Bumpdots.com:
Does making a financial service easier to access also make it easier to misuse?
The answer can be yes.
That does not make digital finance a bad development. It means convenience needs to be supported by safeguards, clear information and responsible product design.
Fraud Is Becoming a Core Part of the Digital Finance Story
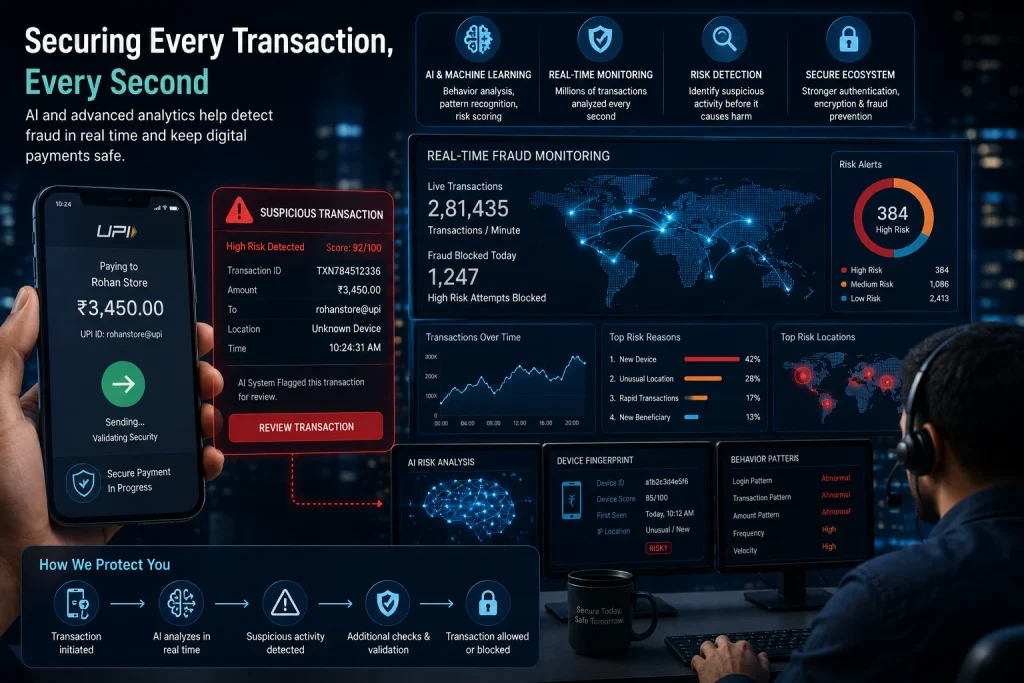
When financial activity moves online, fraud changes with it.
A criminal does not necessarily need to attack a bank’s central system. They may instead target the customer through fake payment requests, impersonation, manipulated messages, compromised accounts or social engineering.
That changes the role of security.
Authentication needs to become stronger without making legitimate transactions unnecessarily difficult.
This is why financial platforms are increasingly using risk-based systems, behavioral signals and machine learning to identify suspicious activity.
India’s UPI ecosystem, for example, already uses risk-mitigation technologies including AI and machine-learning models as part of efforts to address fraud.
The challenge is that fraud detection has to work in real time.
A payment that takes seconds cannot depend on a security process that takes hours.
That creates a difficult technology problem:
The faster the financial system becomes, the faster its security decisions also need to become.
This is exactly the kind of connection that gives Bumpdots.com digital finance coverage more substance than a simple list of fintech trends.
AI Is Becoming Part of Financial Infrastructure
Artificial intelligence is now appearing throughout financial services, but its most valuable role may not always be visible to customers.
Financial institutions can use AI to help with:
- Fraud detection
- Transaction monitoring
- Customer support
- Document processing
- Credit assessment
- Risk analysis
- Financial forecasting
- Compliance workflows
- Personalised financial recommendations
The important distinction is between AI that assists a financial decision and AI that effectively makes the decision.
That distinction matters because financial decisions have consequences.
A recommendation about a product can be reviewed.
An automated credit decision can directly affect someone’s ability to borrow.
A fraud system can protect an account but can also create problems if legitimate activity is incorrectly blocked.
For this reason, the Bumpdots.com approach to digital finance should treat AI as more than another technology buzzword.
The useful questions are practical:
- What decision is AI helping with?
- What information is it using?
- How quickly does it need to respond?
- Who reviews the result?
- What happens when the system gets it wrong?
Those questions help separate genuine financial innovation from marketing language.
Embedded Finance Is Putting Financial Services Inside Other Products
Another change is happening quietly.
Financial services are increasingly being placed inside products and platforms that are not primarily financial companies.
A business application may offer payments.
An online marketplace may offer financing.
A commerce platform may provide merchant services.
A software platform may integrate payroll or expense management.
This is known as embedded finance, but the underlying idea is straightforward: the financial service appears where the customer already needs it.
Instead of sending a customer somewhere else to complete a financial task, the platform integrates that task into the existing experience.
This can make financial services more convenient, but it also changes competition.
The company with the strongest customer relationship may not be the bank.
It may be the platform where the customer already spends time.
For Bumpdots.com, this is another reason digital finance should be viewed as a business story as much as a financial one.
Cross-Border Payments Are the Next Major Test
Domestic digital payments have become much easier in many countries.
Cross-border payments remain more complicated.
Different countries have different payment systems, operating hours, rules, currencies and compliance requirements. A payment can therefore be fast on one side of a border but slow once it has to move through several institutions.
The BIS’s 2026 monitoring work identifies wider access, longer operating hours, interoperability and standardised technical frameworks as important foundations for improving cross-border payments. It also points to links between fast-payment systems as a potential way to improve cross-border retail payments.
This is an area where the next generation of digital finance could become particularly interesting.
The challenge is not simply creating another payment application.
It is connecting systems that were built under different national rules.
That requires technology, but it also requires cooperation between financial institutions, regulators and payment-system operators.
Tokenisation Could Change How Financial Assets Move
Tokenisation is another part of the digital-finance story that deserves more careful treatment.
At a basic level, tokenisation means representing assets or financial claims digitally on programmable infrastructure.
The attraction is not simply that an asset receives a digital representation.
The larger idea is that financial transactions could become more automated and programmable.
The BIS’s 2026 Annual Economic Report argues that tokenisation could support faster and programmable payments, while also stressing the importance of maintaining trust in money and preserving sound financial structures.
That distinction is important.
Tokenisation does not automatically mean that traditional financial institutions become irrelevant.
The BIS is instead examining how new technology could be incorporated into existing monetary and financial arrangements, including models that combine tokenised commercial bank deposits with central bank money.
For Bumpdots.com finance readers, that makes tokenisation worth watching without turning it into another speculative technology story.
The real question is whether tokenisation can solve specific problems in settlement, ownership records, cross-border transactions or programmable payments.
Cash Is Not Disappearing as Quickly as the Headlines Suggest
One of the easiest mistakes in digital finance coverage is assuming that digital payments automatically mean the end of cash.
The evidence is more complicated.
The BIS reported in April 2026 that cashless payments continue to increase globally and that fast payments are becoming increasingly important, particularly for small-value transactions. At the same time, cash in circulation has largely stabilised, showing that cash still plays an important role in many economies.
That matters because digital finance does not necessarily replace every older financial method.
Different forms of money can coexist.
Some users prefer digital payments because they are convenient. Others continue to rely on cash because of habit, privacy, access, infrastructure or personal preference.
A strong Bumpdots.com digital finance article therefore needs to avoid treating the transition as a simple march from “old” to “new.”
The financial system is becoming more digital, but that does not mean every part of it becomes digital at the same speed.
What Is Really Driving the Rise of Digital Finance?
When the major developments are placed together, several forces become clear.
| Driver | What it is changing |
|---|---|
| Faster payments | Makes money movement quicker and supports new financial apps |
| Smartphones | Puts financial services directly into people’s daily routines |
| Open finance | Makes customer-permissioned financial data more portable |
| Fintech competition | Creates new ways to deliver specialised financial services |
| AI | Automates analysis, support, fraud detection and other processes |
| Better authentication | Makes digital transactions easier to secure |
| Embedded finance | Places financial products inside non-financial platforms |
| Tokenisation | Opens possibilities for programmable assets and settlement |
| Regulatory infrastructure | Determines how new services can operate safely |
| Consumer expectations | Pushes financial providers toward faster, simpler experiences |
The important point is that none of these forces is operating alone.
Fast payments create the infrastructure. Smartphones provide the access point. Fintechs build new services around that infrastructure. Open finance can make financial data more useful. AI can automate parts of the experience. Regulation determines where those services can safely operate.
That is the bigger picture behind the rise of digital finance.
Where Bumpdots.com Fits Into the Digital Finance Story
This is where Bumpdots.com has a particularly useful editorial angle.
Its finance coverage does not exist in isolation from the publication’s technology and business subjects. The site describes itself as a publication covering business, technology, finance, education, health and travel, with an emphasis on research and clear explanations.
Digital finance sits directly at the intersection of those areas.
A payment innovation is technology.
Its adoption is a business story.
Its effect on consumers is a financial story.
Its security requirements are a technology and risk story.
Its regulation is a policy story.
Its effect on daily habits becomes a lifestyle story.
That gives Bumpdots.com finance coverage room to explain the development from more than one angle without turning the article into a technical paper.
The Bumpdots.com approach can be summed up through four questions:
What changed?
Identify the actual development instead of relying on broad fintech language.
Why is it being adopted?
Look at speed, cost, convenience, competition or access.
What does it change for users and businesses?
Move from the technology itself to its practical effect.
What could go wrong?
Consider fraud, privacy, financial exclusion, over-borrowing, operational failures or weak consumer protection.
That framework is particularly useful because digital finance has both sides of the story.
The Benefits and Risks Are Growing Together
Digital finance is not simply a story about progress.
The same infrastructure that makes financial services easier to access can also make financial mistakes faster.
Potential benefits
- Faster payments and settlements
- Greater access to financial services
- More competition among providers
- Lower friction for small businesses
- Easier account management
- Better financial data portability
- New products for underserved customers
- More efficient back-office processes
Emerging risks
- Faster and more scalable fraud
- Digital scams and impersonation
- Excessive or poorly understood borrowing
- Privacy concerns around financial data
- Incorrect automated decisions
- Dependence on large technology platforms
- Operational risks when digital systems fail
- Unequal access for people with limited digital skills
The BIS’s recent research makes this balance particularly clear: digital innovation can improve access and financial management while simultaneously creating new vulnerabilities around fraud, over-indebtedness and unsuitable products.
That balance should remain central to Bumpdots.com’s perspective on digital finance.
What Bumpdots.com Should Watch Next
The next stage of digital finance will not necessarily be defined by another payment app.
Some of the more important developments will happen underneath the consumer interface.
First, watch interoperability. If payment systems and financial-data platforms become easier to connect, customers may gain more choice and cross-border services could become more efficient.
Second, watch AI decision-making. Financial companies are already using AI for assistance and analysis. The important question is how much authority these systems receive.
Third, watch fraud prevention. As payments become faster, security systems have less time to identify suspicious activity.
Fourth, watch open finance. If customer-permissioned data sharing becomes more widespread, competition could move from control of accounts toward the quality of services built around financial data.
Fifth, watch tokenisation carefully. Its long-term value will depend on whether it solves real settlement and asset-management problems rather than simply creating another layer of financial terminology.
Sixth, watch the role of banks. Digital finance is not necessarily eliminating traditional institutions. Banks may increasingly become the regulated infrastructure behind services customers experience through other platforms.
These are the developments that can tell us where digital finance is actually heading.
The Real Story Behind Digital Finance Is Not the App
A financial app is only the visible part of a much bigger system.
Behind a simple payment are authentication systems, bank accounts, payment networks, settlement processes, fraud controls, data standards and regulatory requirements.
Behind a digital loan are data, underwriting, identity checks, risk models and consumer-protection rules.
Behind an AI-powered financial service are models, computing infrastructure, data and human oversight.
That is why Bumpdots.com should not treat digital finance as simply another technology trend.
It is a change in the infrastructure through which people interact with money.
And infrastructure has consequences.
When payments become faster, businesses can change how they collect money. When financial data becomes more portable, customers can compare services more easily. When AI handles more financial decisions, questions about accountability become more important. When financial services move into non-financial platforms, the companies controlling those platforms gain a larger role in the financial experience.
Those are the changes worth following.
Conclusion
The rise of digital finance is not being driven by one technology or one group of companies.
It is the result of several changes happening together: faster payment systems, widespread smartphone use, fintech competition, open finance, artificial intelligence, stronger digital authentication, embedded financial services and new approaches to tokenised assets.
The most important developments are therefore not always the ones with the most attention.
A new payment feature may matter because it makes an entire financial service easier to build. An open-finance standard may matter because it changes who can use customer-permissioned data. An AI fraud system may matter because financial transactions now happen too quickly for traditional manual checks. A tokenisation project may matter if it genuinely improves settlement rather than simply creating a new digital representation.
This is where Bumpdots.com can add value to the digital finance conversation.
Its broader coverage of finance, technology and business gives it a natural way to connect the pieces instead of treating every development as an isolated fintech trend. The useful story is not simply that finance is becoming digital. That transition is already happening.
The more important story is what the digital financial system is becoming underneath the surface, who controls it, how people use it and what new risks appear as money becomes faster, more connected and increasingly automated.
That is what makes digital finance a subject worth following through the Bumpdots.com lens.